Fixed vs Floating Interest Rate: Which Loan Option Should You Choose? | LoanSathi.in
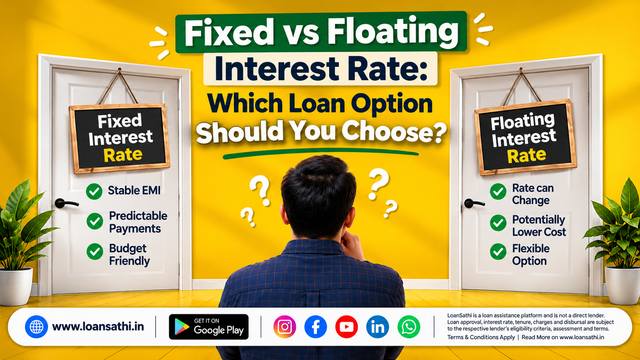
Choosing the right interest-rate structure can make a meaningful difference to your total loan cost. If you are comparing a fixed interest rate with a floating interest rate, the right choice depends on your loan type, repayment period, financial comfort and expectations about future rate movements. LoanSathi.in helps customers compare available loan options through a network of 150+ banks and NBFCs.
Fixed vs Floating Interest Rate: Which Loan Option Should You Choose?
Quick Overview
Fixed vs Floating: What Is the Difference?
With a fixed interest rate, the applicable rate remains fixed for the period specified in the loan agreement. This can make budgeting easier because your interest cost is more predictable during that period.
With a floating interest rate, the applicable rate may move up or down when the lender's benchmark or other contractual pricing conditions change. This means your EMI, loan tenure or both may change depending on the lender's terms.
Which Option May Suit You?
Select the statement that describes your priority:
5 Things to Check Before Choosing
- Loan Tenure: A longer repayment period can expose you to more changes in the applicable rate when using a floating structure.
- EMI Comfort: Check whether your monthly budget can comfortably handle a potential increase in repayment.
- Rate Terms: Do not compare only the headline rate. Review the reset frequency, benchmark, spread and applicable conditions.
- Total Cost: Compare the overall repayment obligation rather than looking only at the starting EMI.
- Future Plans: If you expect to repay early or refinance, check foreclosure, prepayment and other applicable charges.
Fixed or Floating: A Simple Comparison
How the LoanSathi Process Works
LoanSathi is a loan assistance platform and does not directly lend money. The process is designed to help customers understand suitable loan options from the available lender network.
After the customer confirms the available offer, the team proceeds with the lender application. The final approval, interest rate, tenure and disbursal are subject to the selected lender's eligibility assessment and terms.
Explore available categories through LoanSathi Products or learn more about the 150+ Banks & NBFC Network.
Explore Loan Options
Compare Your Loan Options With LoanSathi
The right rate structure depends on your profile, lender terms, loan amount and repayment plan. Review the available offer carefully before making a decision.
Visit LoanSathi.in View Loan ProductsFrequently Asked Questions
Is a fixed interest rate always better than a floating rate?
No. Neither structure is automatically better for every borrower. Your choice should depend on repayment comfort, loan tenure, lender terms and your ability to manage possible rate changes.
Can a floating interest rate change during the loan?
Yes. A floating rate can change according to the benchmark, reset mechanism and other conditions specified by the lender.
Does LoanSathi decide the final interest rate?
No. LoanSathi assists with the loan process. The final interest rate, eligibility, tenure, approval and disbursal are decided by the lender based on its assessment and applicable terms.
Can I compare offers from different lenders?
Yes. LoanSathi can assist customers in exploring available options across its 150+ bank and NBFC network, subject to lender eligibility and product availability.
What should I check before accepting an offer?
Check the interest rate, EMI, tenure, total repayment, processing charges, prepayment or foreclosure terms and all other applicable charges before accepting the lender's offer.


